
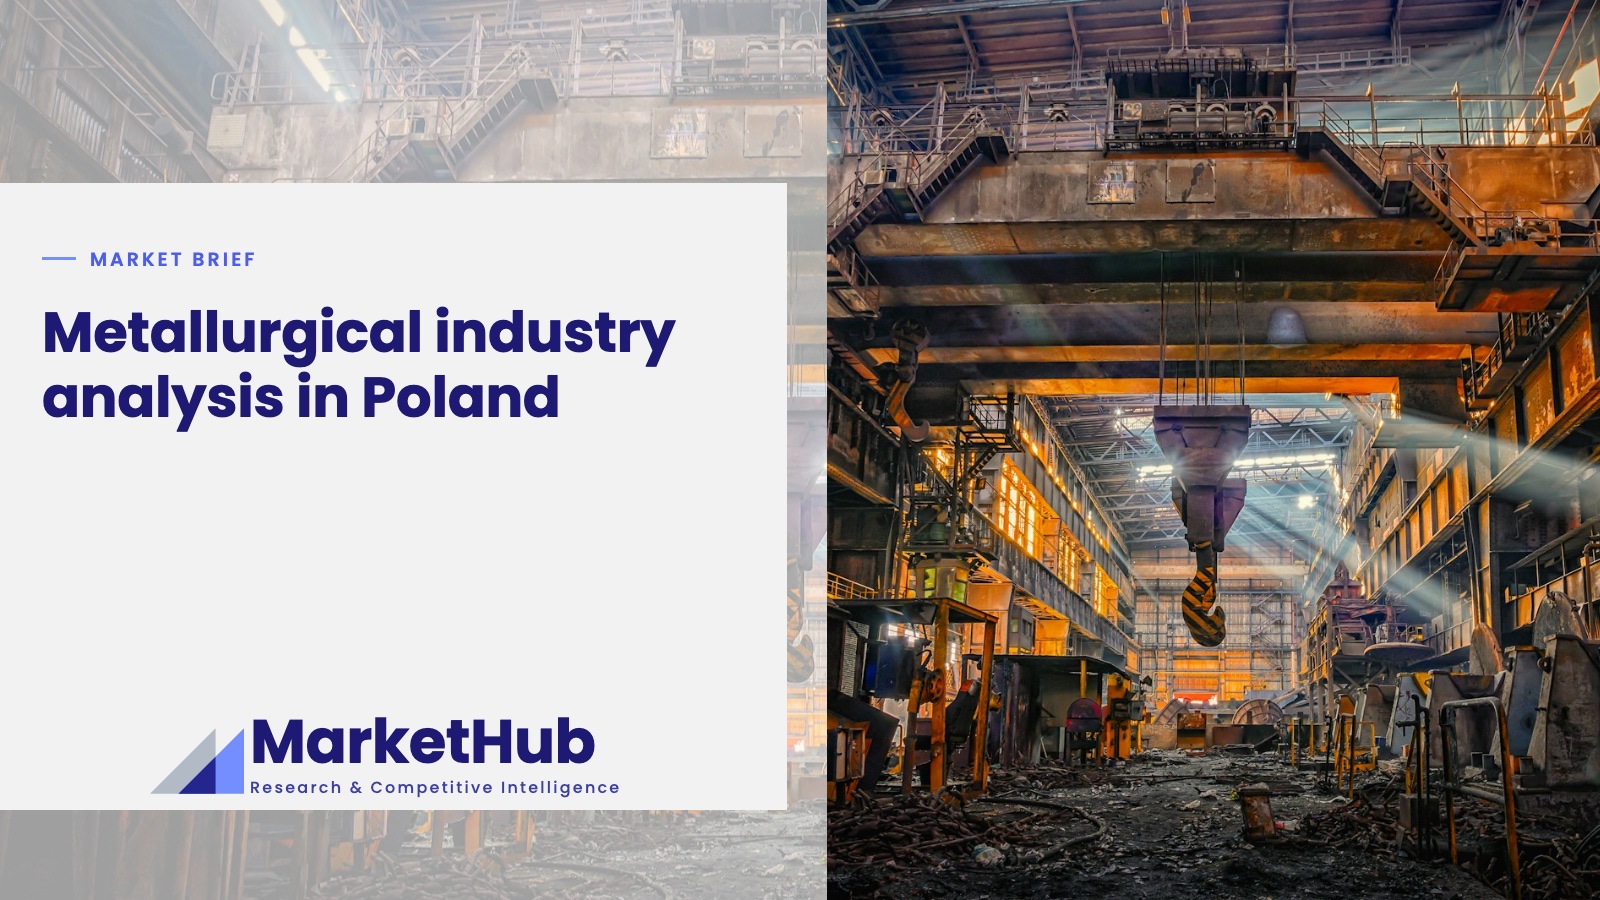
Metallurgical industry analysis in Poland
Our analysis of the metallurgical market shows that this sector has a long tradition in Poland. It is overwhelmingly a private market (approx. 97% of companies) and is based on the production and processing of steel. According to World Steel Association forecasts, demand for steel will rise by 50% by 2050. However, changes in the business and legal environment have made steel production in the EU unprofitable, which is pushing metallurgical production out of the EU.
Need ready-made market data? See the reports in Market Scan.
See the scan catalogueUnder the terms agreed with the European Commission, the production capacity of the steel industry in Poland was 12.6 m tonnes a year until November 2020. Since then it has been 10.6 m tonnes, owing to the shutdown of the primary (iron-making) part of the Kraków plant. Metals account for 5.9% of the value of sold production of Polish industry.
Metallurgy is an important link in recycling for other industries, generating 6.5 m tonnes of scrap a year. Scrap is a decarbonised raw material, and Poland makes a significant contribution to its recovery. Meanwhile, the European Union exports approx. 20 m tonnes of scrap a year, of which approx. 1.5–2 m tonnes comes from Poland.
The undisputed leader of the global steel market is China, which accounts for 51% of crude steel production. Poland ranks 20th among the largest steel producers in the world (7.9 m tonnes in 2020). However, it still has low per capita consumption (13 m tonnes) compared with many EU countries. In addition, Poland is the largest net importer of steel in the EU.
According to the president of the Polish Steel Association (Hutnicza Izba Przemysłowo-Handlowa), as steel-consuming sectors (mainly the automotive and construction industries) stabilise, consumption will return to pre-pandemic levels in 2021. In the long term, it may reach as much as 16 m tonnes a year.
01
Who leads the metallurgical market in Poland?
The largest player is ArcelorMittal, which accounts for approx. 70% of the country's production capacity, out of 2,200 enterprises producing metals in Poland.
According to data from Statistics Poland (GUS), there are 2,200 enterprises producing metals in Poland. At the beginning of 2021, 19 new entities were registered, including HUTMEN with share capital of PLN 256 m. The Polish Steel Association (HIPH) monitors the market situation of metallurgical companies in Poland on an ongoing basis.
The world's largest producer of crude steel, ArcelorMittal, also has assets in Poland. The company accounts for approx. 70% of the country's production capacity. It has plants in Dąbrowa Górnicza, Chorzów, Sosnowiec, Świętochłowice, Zdzieszowice and Kraków. Two years ago the group decided to temporarily shut down the primary (iron-making) part of its Kraków plant. The blast furnace was scheduled to restart in the second half of March 2020, but the COVID-19 pandemic first postponed this, and in October the group announced its permanent closure. As a result, Poland irreversibly lost 2 m tonnes of production capacity. To make up for the losses, the company invested in its Kraków processing operations by modernising the pickling line in the cold rolling mill.
02
How do climate regulations affect the steel industry in Poland?
Regulations aimed at climate neutrality, together with higher prices of electricity and carbon dioxide emission allowances (EU ETS), are making Polish metallurgical companies uncompetitive against producers from third countries.
Many of the changes being implemented in the metallurgical market result from regulations introduced to achieve climate neutrality. Despite deep technical and technological restructuring in the first decade of the 21st century, the steel industry is still one of the three most energy-intensive manufacturing industries, and a mere 1 terajoule a year of its final energy consumption comes from renewable sources (solid biofuels).
Higher prices of electricity and of carbon dioxide emission allowances (EU ETS), as well as the lack of effective measures to protect the European market, are making Polish metallurgical companies uncompetitive against producers from third countries. To win back market share, they need costly investment in decarbonisation and an attempt to introduce certified production of "green steel" on a mass scale.
03
What does the White Paper on Industrial Development propose for metallurgy?
Published in February 2021 by the Ministry of Development, Labour and Technology, the White Paper proposes, among other things, lower wholesale electricity prices, changes to the compensation system for energy-intensive sectors and support for CO2 emission reductions.
In February 2021 the Ministry of Development, Labour and Technology published the "White Paper on Industrial Development" with proposed solutions to problems observed in industry. A large section of it was devoted to metallurgy. It presented ideas for changes such as:
Author: Kamila Nowak
Sources:
Value of sold production of industrial products, Statistics Poland (GUS).
Structural changes in groups of entities of the national economy in the REGON register, Statistics Poland (GUS).
Statistical Yearbook of Industry, Statistics Poland (GUS).
Energy balances in the "Manufacturing" section, Statistics Poland (GUS).
Energy 2020, Statistics Poland (GUS).
White Paper on Industrial Development, Ministry of Development, Labour and Technology.
Polish Steel Association (Hutnicza Izba Przemysłowo-Handlowa), www.hiph.org.
World Steel Association, www.worldsteel.org.
Industry monitoring, steel market analysis.
These technologies could completely change the world, energetyka.
ArcelorMittal Poland will permanently close the primary (iron-making) part of the Kraków steelworks.
Ready-made market reports in PDF
Market Scan by MarketHub has ready-made PDF reports on selected markets: market size, key players, trends and data sources. If your market is not covered, we will prepare an in-depth market analysis.
Want to use this brief?
You can quote the data if you name the source and, where possible, link to our website. Use this credit line:
Source: MarketHub, "Metallurgical industry analysis in Poland", markethub.pl, 05.2021