
Petrochemical market analysis
The countries with the largest production capacity for petrochemical products are China, India, Iran, Russia and the USA. This does not mean, however, that Poland is not investing in petrochemicals. This market analysis shows what the refining and petrochemical market looks like and how it is developing.
Need ready-made market data? See the reports in Market Scan.
See the scan catalogueThe pandemic, which caused a sharp economic slowdown, clearly affected the crude oil market. In 2020 global crude oil processing fell by 9%. According to forecasts, the refining and petrochemical market will record further declines in the coming years. The best chance of success lies with countries that have the most efficient and modern installations for processing the raw material and the intermediate products made from it. Simple production of liquid fuels from oil is becoming less and less important, while technologically advanced petrochemical products are playing a growing role.
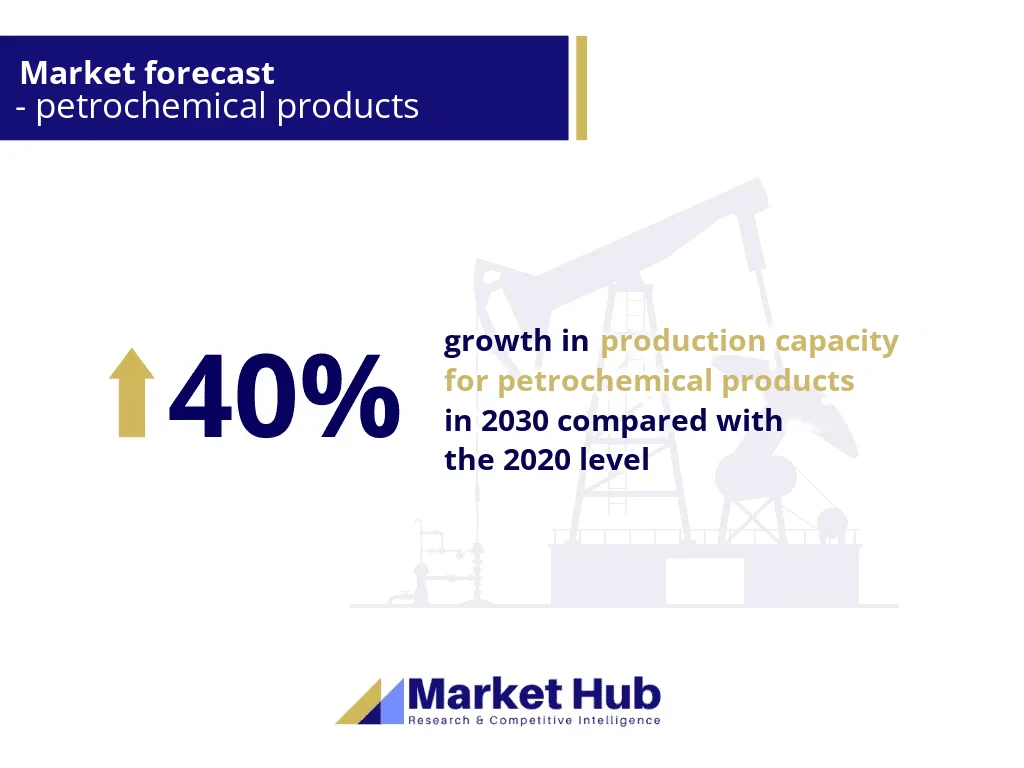
GlobalData analyses show that by 2030 global production capacity for petrochemical products will be more than 40% higher than in 2020. Forecasts indicate that the most capacity will be built in China, followed by India, Iran, Russia and the USA. No EU country is among the leaders in planned petrochemical investment. This does not mean, however, that such projects are not being carried out.
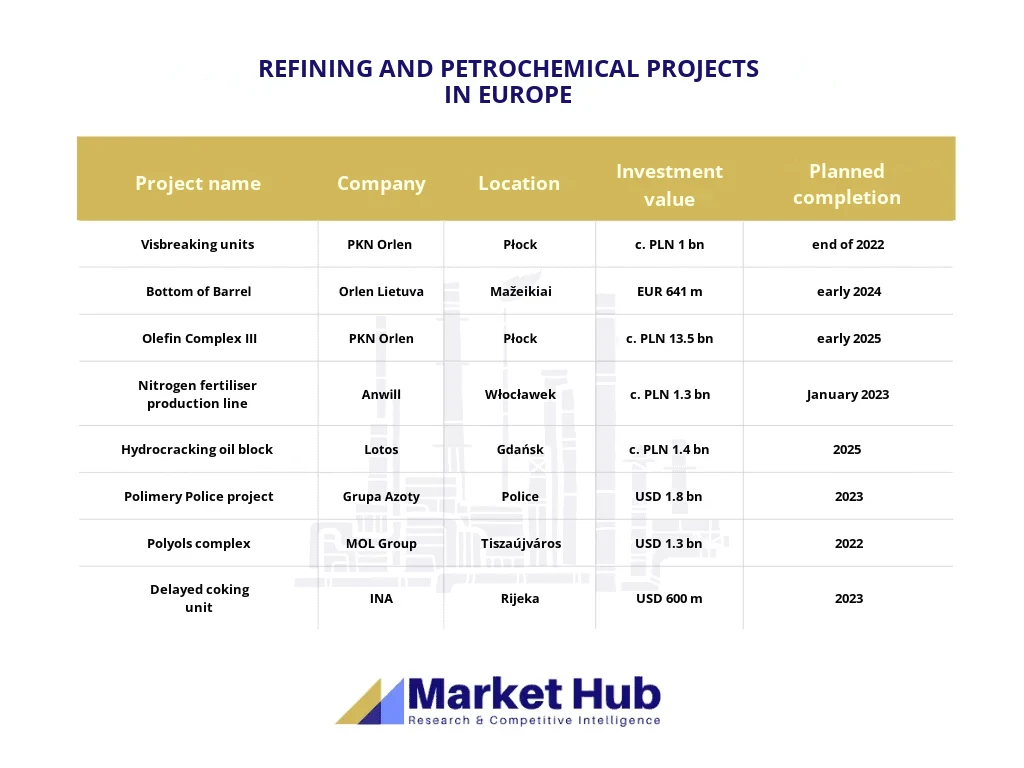
The largest programme to modernise refining and petrochemical installations in Central and Eastern Europe is the Orlen group's Olefin III, worth approx. PLN 13.5 billion. It will process various intermediate products from crude oil refining and will need approx. 1 million tonnes of them, most of which will be supplied by the group's refineries.
01
How big are retail fuel sales in Poland?
Estimates by the Polish Organisation of Oil Industry and Trade (POPiHN) show that retail sales of motor fuels in Poland in 2020 were around PLN 109 billion. Preliminary figures put the volume of fuel sold at filling stations at 26.7 billion litres (motor petrol, diesel and autogas). Budget revenue from the taxes paid on these sales (VAT, excise duty, fuel charge, emission charge) was around PLN 65 billion.
According to POPiHN data, in 2020 there were 7,739 public filling stations in Poland selling at least motor petrol and diesel. The largest share was held by domestic oil companies (2,300 stations), followed by foreign oil companies (1,500 stations) and independent networks operating under a common brand (1,100 stations). A smaller share was held by other independent operators (2,400 stations) and stations located at retail stores (187 stations).
02
Who leads the filling station market in Poland?
At the end of 2020 PKN Orlen had the largest share of the Polish filling station market (23.4%), followed by BP (7.4%) and Grupa LOTOS (6.6%).
The structure of the Polish filling station market at the end of 2020 was as follows:
In 2020, as in previous years, PKN ORLEN had the most stations in Poland. BP came second and Grupa LOTOS third. The domestic oil companies still operated under four brands, though on an ever smaller scale: ORLEN and BLISKA (in the case of PKN ORLEN) and LOTOS and LOTOS OPTIMA (in the case of Grupa LOTOS). The number of ORLEN stations bearing the BLISKA logo fell by 11, leaving only 25 at the end of the year. The number of Grupa LOTOS economy stations decreased by 8, to 186. The number of stations operating under the logos of foreign oil companies active in Poland increased. At the end of 2020, 1,569 sites operated under their brands, 26 more than in the previous year. Among independent filling stations, the MOYA network, Grupa Pieprzyk and AVIA grew the most.
03
How many filling stations are there on Polish motorways?
In 2020 there were 90 filling stations on Polish motorways, 6 more than in 2019, and PKN Orlen had the most of them, with 36 sites.
With the expanding network of expressways and motorways and more drivers wanting to travel fast, the number of filling stations on Polish motorways has increased. In 2020 there were 90 of them, 6 more than in 2019. PKN Orlen has the largest share in this category, with stations at 36 Motorway Service Areas (MOP). Grupa LOTOS comes second with 23 sites, followed by BP (16 sites), SHELL (12 sites) and CircleK (2 sites).
Fuel prices on expressways are usually considerably higher than elsewhere. Even so, drivers still use these stations, as they do not want to waste time searching for cheaper alternatives near the main road.
Author: Dominika Będkowska
Sources:
This text is not a full market analysis of the kind we carry out for our clients. It contains only selected information about the market, which we can expand on request.
Ready-made market reports in PDF
Market Scan by MarketHub has ready-made PDF reports on selected markets: market size, key players, trends and data sources. If your market is not covered, we will prepare an in-depth market analysis.
Want to use this brief?
You can quote the data if you name the source and, where possible, link to our website. Use this credit line:
Source: MarketHub, "Petrochemical market analysis", markethub.pl, 03.2022